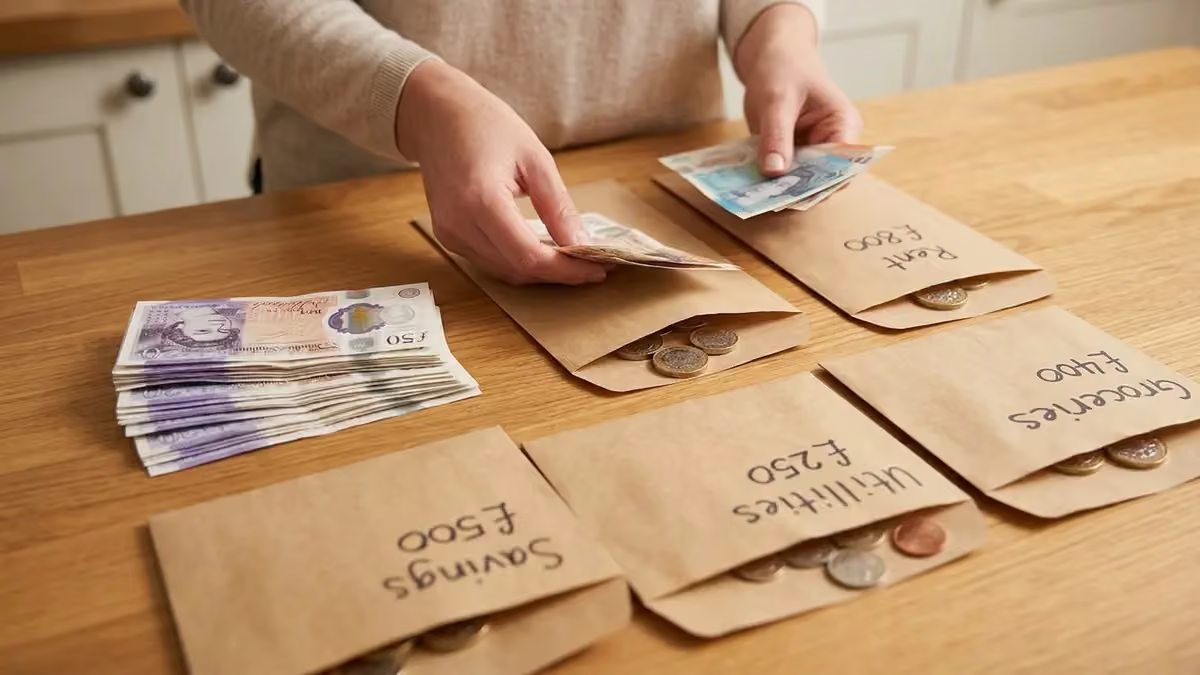
One clear benefit of envelope budgeting is that it prevents overspending. You divide your money into envelopes for each spending category, such as groceries, fuel or entertainment, and once an envelope is empty, spending in that category stops until the next budget period. There is no room to quietly go over.
That hard limit is what makes the method so effective. Instead of tracking spending after the fact and discovering you went over budget, envelope budgeting forces the decision at the moment of purchase. You can literally see how much is left.
Envelope Budgeting at a Glance
| Item | Summary |
| What it is | A budgeting method that splits money into separate envelopes for each spending category |
| Main benefit | Stops overspending by setting a hard limit per category |
| Other benefits | Spending awareness, less debt use, easier conversations about money |
| Traditional format | Physical cash in labeled paper envelopes |
| Modern format | Budgeting apps or separate bank sub-accounts |
| Best for | People who overspend on variable categories or rely on credit cards |
| Main drawback | Less convenient, cash can be lost, not ideal for online purchases |
How Envelope Budgeting Works
The method is simple enough to explain in a few sentences, which is part of its appeal.
When you get paid, you decide how much to spend in each category for the period. Then you put that amount of cash into an envelope labeled with the category. Groceries get one envelope, dining out another, fuel another and so on.
When you shop for groceries, you take the grocery envelope and pay from it. If the envelope runs out three days before payday, you either make do with what is in the pantry or move money from another envelope, which means less to spend there.
Fixed bills like rent, insurance and loan payments usually stay in the bank and get paid automatically. The envelopes are for the flexible spending where most budgets fall apart.
A Sample Monthly Setup
| Envelope | Monthly Amount | Notes |
| Groceries | $500 | Split into weekly amounts for better pacing |
| Fuel | $180 | Refilled each payday |
| Dining out | $120 | Easiest envelope to overspend without limits |
| Entertainment | $80 | Movies, hobbies, subscriptions not on autopay |
| Personal care | $60 | Haircuts, toiletries |
| Gifts | $50 | Builds up for birthdays and holidays |
| Miscellaneous | $75 | Small surprises |
Amounts are only an example. Your numbers should come from your own income and past spending.
Why the Spending Limit Matters So Much
Most budgets fail for a predictable reason. They are plans that rely on willpower, and willpower is weakest at the checkout counter.
Card payments make spending feel abstract. You tap, the purchase goes through and the money leaves an account you rarely look at. Research on payment methods has long suggested that people tend to spend more with cards than with cash, partly because handing over physical money feels like a real loss.
Envelope budgeting reverses that. When you can see three twenty-dollar bills left in the dining out envelope on the 18th of the month, the decision about whether to order takeout tonight becomes very concrete.
There is also no “I’ll make it up next month” escape. The money is either in the envelope or it is not.
Other Benefits Worth Knowing
Overspending control is the headline benefit, but people who stick with the method often mention several others.
You Become Aware of Where Money Goes
Many people are genuinely surprised the first month they try envelopes. A category they thought cost $100 actually costs $250. That awareness alone often leads to better choices.
It Reduces Reliance on Credit Cards
If you pay for flexible spending with cash or a fixed digital balance, you are not building up card debt on everyday purchases. For anyone trying to get out of debt, this is a big deal.
It Makes Priorities Visible
Deciding how much goes into each envelope is a values exercise. It pushes you to choose what matters most, whether that is eating out with friends or saving for a trip.
It Simplifies Money Talks With a Partner
Couples often argue about spending because the rules are unclear. Envelopes make the rules visible. If the entertainment envelope is empty, there is nothing to argue about.
It Builds Saving Habits
Money left in an envelope at the end of the month can roll over or move into savings. Many people find that leftover cash is the most satisfying part of the whole system.
| Benefit | What It Looks Like in Daily Life |
| Overspending control | You stop buying when the envelope is empty |
| Spending awareness | You know exactly how much each category costs |
| Less debt | Fewer card purchases for everyday items |
| Clear priorities | Spending reflects choices made in advance |
| Easier partner conversations | Shared rules that both people can see |
| Saving habit | Leftover money is visible and easy to redirect |
The Drawbacks, Honestly
Envelope budgeting is not perfect, and pretending otherwise sets people up to quit.
Carrying cash is less convenient than it used to be. Some businesses do not accept cash at all, and online shopping requires a card.
Cash can be lost or stolen, and there is no fraud protection on a stolen envelope.
You give up card rewards and cashback on purchases made with cash.
And it takes some setup and discipline in the first few months, especially when you are still figuring out realistic amounts.
None of these are deal breakers, but they explain why many people now use a digital version instead.
Cash Envelopes vs. Digital Envelopes
Modern budgeting apps and banks have adapted the envelope idea for people who rarely use cash.
| Format | How It Works | Pros | Cons |
| Physical cash | Labeled envelopes with real money | Strongest spending feedback, no tech needed | Inconvenient, risk of loss, no online use |
| Budgeting apps | Digital categories with set limits | Works with cards, tracks automatically | Easier to ignore, may need subscription |
| Bank sub-accounts | Separate accounts or “pots” for each category | Money is truly separated, works online | Moving money takes small extra steps |
| Prepaid or dedicated cards | One card per category or loaded with limits | Card convenience with a hard cap | Possible fees, more cards to manage |
Many people use a mix. Cash for categories they tend to overspend, like dining out and groceries, and digital envelopes for everything else.
How to Start Envelope Budgeting
Getting started does not require special tools. A few envelopes and a pen will do.
Look at the last two or three months of spending to see what you actually spend in each flexible category.
Choose a small number of envelopes to begin with. Four to six is plenty. Groceries, fuel, dining out and entertainment are common starting points.
Set amounts based on reality, then trim slightly. Cutting a category in half on day one usually leads to frustration.
Fill the envelopes on payday so the rhythm becomes automatic.
Decide your rules in advance. Can you borrow from one envelope to cover another? What happens to leftover money? Clear rules prevent second-guessing later.
Review after a month and adjust. The first month is about learning, not perfection.
Common Mistakes When Starting Out
Most people who give up on envelope budgeting do so in the first two months, usually for avoidable reasons.
Setting amounts too low is the most common one. If your grocery envelope is half of what you normally spend, you will run out in the second week and feel like the system failed. Start realistic and trim gradually.
Forgetting irregular expenses is another. Car registration, annual subscriptions and school costs catch people off guard. A small “annual expenses” envelope filled every month solves this.
Borrowing between envelopes without limits also undermines the method. Moving money occasionally is fine. Doing it every week means the amounts need adjusting.
Finally, some people quit after one bad month. That first month is data, not failure. Adjust the numbers and try again.
Who Envelope Budgeting Works Best For
The method tends to click for people who struggle with variable spending, people paying off debt and anyone who has tried tracking apps but never changed their behavior.
It also works well for people with irregular income, because envelopes force you to plan around what you actually have rather than what you hope to earn.
It may feel restrictive for people who already spend well within their means. If you consistently save money without effort, a simpler budget may be enough.
The Answer in One Line
If you need a single benefit of envelope budgeting, it is this: it stops overspending by putting a firm, visible limit on each category of spending. Everything else, from lower debt to better savings, grows out of that one simple boundary. Sometimes the most effective financial tool is just an envelope with a number written on the front.